Another week, another round of whack-a-mole uncertainty about what's happening to prices, interest rates and world events. The news reports are hopeful but the math is brutally honest about what's really happening: Gas & Diesel are at all time highs, interest rates are trending higher and demand is shrinking fast. Our dollars are losing ground in terms of what we can actually buy with them faster that at any time I can remember while at the same time, incomes and business revenues aren't keeping up. If anything, they're going in the opposite direction.
"Central bankers have their explanations ready—inflation is transitory, supply chains are healing, the economy is resilient. But walk through a supermarket in Stuttgart, a gas station in Phoenix, a pharmacy in Manchester, and you’ll feel the truth your paycheck already knows. The purchasing power hasn’t just eroded; it’s evaporated, and official metrics barely capture the half of it."
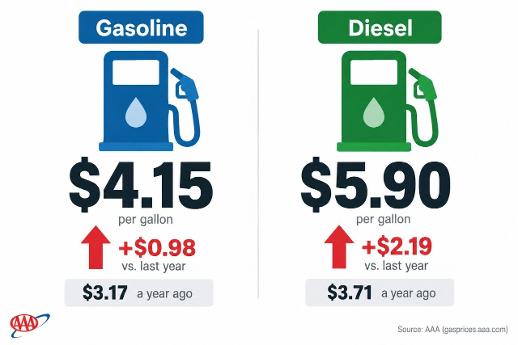
We all depend on a stable economy to maintain our businesses and lifestyles but this condition is killing us by 1000 cuts every day. Diesel costs affect everything except the living standards of the clowns making the rules. THEY can afford this, we can't. Diesel costs are now responsible for a huge portion of the cost increases we all have to pay from the grocery store to the pharmacy.
"Since 2008, and with terrifying acceleration during the pandemic years, monetary expansion has become the silent thief in everyone’s pocket. The Federal Reserve’s balance sheet hovered below $1 trillion in 2008. By 2022, it had ballooned to nearly $9 trillion. Even after some reduction, it sits above $7 trillion. This wasn’t money earned or produced. It was conjured through digital ledger entries, diluting every existing dollar in circulation. Official inflation numbers—those seven to nine percent figures you see in headlines—exclude the categories that actually determine whether families make it to the end of the month. Add housing, energy, and food back in, and you’re looking at fifteen to twenty percent erosion of purchasing power over five years. Ask any wage earner. They’ll tell you the official numbers feel like fiction."
Many of my readers and clients say: "Ok, things are bad, we get it. What can we DO about it?"
Awareness is the first step. By now, reality has smacked everyone who isn't an elite bubble dweller in the face so no one needs to be convinced despite all the happy talk from media which just eliminates whatever shred of credibility they still had. Next, preparedness. That is an individual choice and the level of preparedness differs from one person (or business) to another. Expectations drive policy so it's important to make accurate estimates about what future conditions will look like and what needs should be prioritized over others.
Taking on debt right now should be done purposefully with care. Make a specific plan about how the proceeds will be used with realistic, even conservative estimates about expected results. Purchasing a new truck for a logistics company for example should be accompanied by a realistic calculation of what you can charge on a dollar-per-mile basis. Those numbers should show plenty of room for changes since one headline regarding tariffs or some other unpredictable global event could trash even the most conservative estimates.
There are developments regarding credit scoring that could make accessing capital easier but that won't help to predict future conditions with any kind of confidence. FICO scores are the bane of both lenders and borrowers' existence. A sub-650 score can mean the difference between a 7% and 25% rate. Huge.
It is disturbing to say the least that the FICO scores for everyone are controlled by a monopoly:
"Equifax, Experian, and TransUnion have been overcharging Americans for far too long," Federal Housing Finance Agency Director Bill Pulte wrote on X late Thursday.
The Trump administration's campaign against the cost of credit scores and reports used in the mortgage industry sent shares of Fair Isaac, the company behind FICO scores, as well as Equifax and TransUnion, tumbling on Friday morning.
Pulte continued: "This will end soon. We are seriously considering bi-merge, and stronger solutions (SAFER and SOUNDER). We will not allow companies to take advantage of American consumers. No more."
My BS meter is flashing red right now because, despite all the sanctimonious virtue signaling I believe this move is meant to lower lending standards since defaults have increased to record levels. As much as I despise monopoly's, it won't help our situation if we simply lower the bar and give loans to less credit-worthy borrowers.
If there's one thing holding back more destructive government policy it is the coming November Congressional elections. I believe it's going to be an epic s**t-show but there's a window between now and then to make some preparations. For any businesses looking to borrow capital I suggest getting it done in the next few weeks because after that, the motivations and incentives to manipulate rates lower will be gone regardless of the election outcome.
Math has no politics or political preference; it simply it what it is and ain't what is isn't.
Rates are being held down but they want to go higher since Treasuries are simply toxic right now and nobody what's to own them anymore. The US policy of threatening allies who need to sell Treasuries will just make them want to sell even more and never buy them from us again. Can you blame them? The Treasury and Federal Reserve will definately take measures to prevent rates from increasing however the only weapon they have is to print more dollars further devaluing our existing pool of money units and making everything cost more.
We are currently in a toxic stagflation death-spiral with no apparent exit strategy. In the past, whenever we faced similar problems we had some inteligent leaders in positions of power who understood the problems and took decisive measures to control the repercussions.
Now? Not so much.