The vast majority of my discussions with business owners last week focused on uncertainty. Uncertainty over interest rates, fuel prices, inflation and government policy topped the list but the message from everyone I spoke with was consistent: No one could make any plans with the slightest confidence that things will work out as expected. For years I have seen the warning signs and written many times about what I observed however, now I can say with confidence that the crisis in no longer on the horizon; it is here. Now. Business owners and consumers alike are dealing daily with real-world issues that threaten their living standards and the viability of their companies.
It doesn't help that no one can rely on any news sources to tell us the truth about what is really happening.
Anyone who has been reading this humble blog post the last few years already knows more than all the news pundits put together. I sounds like I'm boasting but truly, all it takes is some time/effort, common sense and an internet connection to discover that most of what we hear on television regarding the economy (or anything really) is complete and utter horsey-pucks.
It helps that I also have ear-to-the-ground access since I speak with business owners every day about their borrowing needs which is what I do for a living. Last week, a business owner in the timber industry with 23 employees told me his fuel bill last month went to $50k which wiped out his margins almost entirely. Truckers in Western states are paying $7/gal for diesel which translates into $1-per-mile on most rigs. Add insurance, driver and maintenance and then compare it to the average of $3-per-mile for most long haul loads and you get the picture. There was talk about a nation-wide trucking strike starting October 1st which never came to pass thankfully but many, many truck owners are simply parking their rigs because they cannot make a profit driving them. No strike. No televised protests. Just a whole lot of rigs we need to deliver supplies parked.
We're in the early innings of this crisis which doesn't have any easy solutions because too many of the issues causing them are structural in nature. The news reports are misleading as usual:
"Economists keep pointing to consumer spending as proof that the American economy remains strong. Americans spent 0.9% more in August, and naturally this is being celebrated as the resilient American consumer. But real disposable income did not increase AT ALL, while the personal savings rate fell to just 4.1%. Americans are spending more while their inflation-adjusted income is going nowhere and savings are being depleted to maintain their standard of living.
The cost-of-living crisis is showing up in the numbers. Consumer spending can rise during inflation simply because everything costs more. If your grocery bill rises from $150 to $200, you increased consumer spending by 33%, but you did not become wealthier or eat 33% more food. You simply handed over more dollars for the same necessities."
Anyone who thinks voting in elections can solve our problems hasn't been paying attention at all.
"The purpose of a system is what it does"
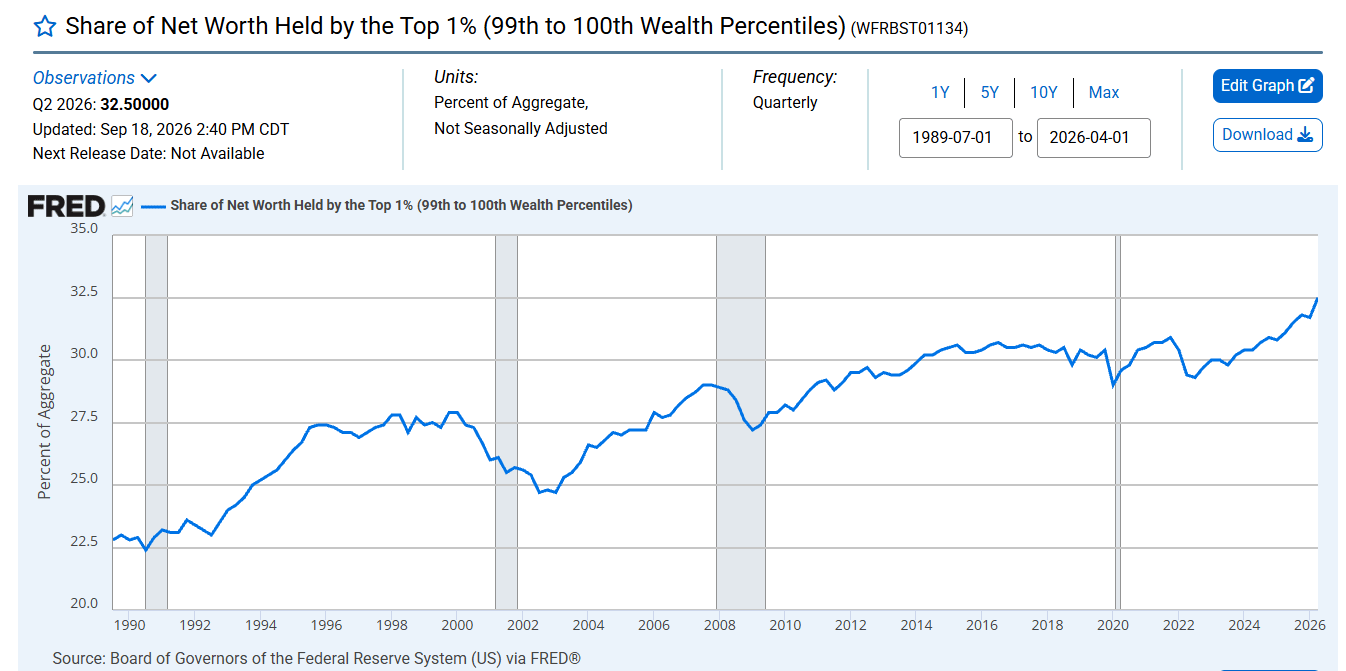
"The ultrawealthy aren’t just pulling away from average Americans. Buoyed by a stock-market boom that has added trillions of dollars to their net worth, the extremely rich are even pulling away from other rich Americans."
I want to make a quick point about the rise in interest rates; Many of you have seen rates going higher on the 10-year Treasury to 5.3% which is consistent with what I have been saying now for quite a while: The Fed doesn't determine interest rates, the market does. Otherwise rates would be zero forever. There is another aspect to this however which is worse than simply making mortgage rates go higher. The value of the Treasuries sold in previous years at MUCH lower interest rates fall in value when current rates rise. Here is an example:
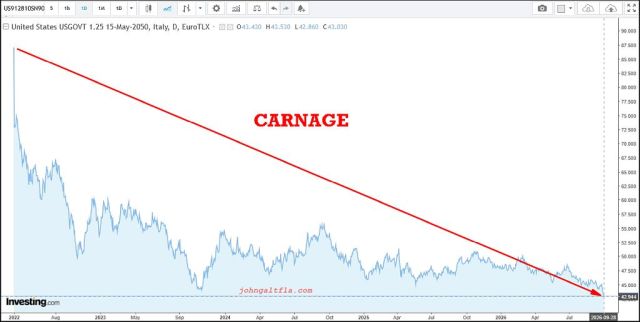
The above chart is for a US 3-yr Treasury issued in 2020 (expires in 2050) with an initial coupon rate (Annual interest) of 1.25%. Guess who owns these POS bonds? Banks. Yes, our banks. Most of them at least but, here's the thing: THEY get to value it at their cost. That is to say, they don't have to show the loss on their books (otherwise known as marked to market) unless they sell it. The banks are allowed by law to hide their paper losses legally by carrying their losers at the price they originally paid for them. Nice work if you can get it!
My point is this: The Billions of Treasuries banks bought at low interest rates (and are currently carrying on their books) are down 50% or more. If they were to be marked at their actual market values, most if not all of those banks would be insolvent. Remember Signature? SVB? 1st Republic? Bernie Madoff lol??
Business owners are getting declined for lines of credit or are getting their existing lines cut back without explanation. When I speak with my lending sources they're telling me that risk aversion is the cause however there's another reason which they aren't saying; they can't sell their Treasury holding to get liquidity needed to make new loans. Those banks would love to put the capital they have in US Treasury bonds to work in higher interest commercial loans but, the can't. If they sell their bonds at a loss they will need a bail-out and that's just not happening right now.
There are private landers and some regional banks that don't have this problem so they're able to make loans where others simply can't compete. That is an advantage that many business owners who qualify can take advantage of.
Why borrow now when there's so much uncertainty? The question answers itself; now is the time to secure a line of credit that gives your company access to critical working capital when you need it to complete or initiate new projects. The ability to secure credit now is a huge advantage because many government and corporate projects will be up for grabs when their existing vendors fall away. I could name a few other reasons such as stockpiling critical inventory to avoid shipping cost increases which are expected to explode higher. Tanker and container ship daily rates have gone from $30k/day to $1 Million/day. Read that again.
With so much going on I can't cover everything here in one post but I'll be back with more next week.
Until then, God bless!